
It’s no more the king within the UAE. With the rise of digital payment options dominating daily expenditure such as DEWA bills to fees for school, Salik top-ups, and weekends brunches, people are increasingly opting for credit cards that allow them to pay back money they already planning to spend. This is the whole appeal of the cashback credit card. it converts routine expenditure into recurring cashback without the complexities of airline miles or reward point conversions.
There is a UAE marketplace for credit cards is well-known as overcrowded including traditional banking institutions, Islamic banking institutions, as well as digital first neobanks trying to attract cardholders. The advertised cashback rates may appear attractive at first glance”10% cashback! “10% cashback!” However, the true value is based on a combination of caps on monthly amounts, minimal spending thresholds, excluded categories and annual charges that typically are hidden in the small print.
This guide explains some of the most popular cashback card options in the UAE for 2026, the amount each of them actually pays when you take into account caps, and also how to match the card to your spending habits.
How We Chose These Cashback Cards?
Before you rank any card, it is helpful to know the factors that determine the cashback card’s worthy of having:
- Cashback effective rate: Amount advertised is less important than the amount you’ll earn in reality once the monthly caps and restrictions on categories are in place.
- Annual fee in comparison to. the cashback threshold: A card with fees must earn more cashback than a card that is free or else the cost will reduce your cashback.
- Minimum requirement for salary: UAE banks set the minimum thresholds for salary to be eligible for credit cards and it varies according to issuer and the tier.
- Redemption procedure: Some cards auto-credit your account with cashback; other cards require manual redemption using an app or by calling a to make a call once the threshold is exceeded.
- Additional benefits: Airport lounge access cinema discounts, insurance may help balance two cards that are priced similarly.
- Shariah Compliance: Several UAE residents specifically search for Islamic banks, which is why it is worthwhile to flag every possibility.
With that in mind With that in mind, these are the top 10 cashback credit cards in the UAE today.
Top 10 Cashback Credit Cards in UAE
1. Mashreq Cashback Credit Card
It is widely regarded as one of the most powerful all-round cashback cards available in the UAE. The Mashreq Cashback Credit Card comes completely free for the rest of your life. There’s no annual fees for the primary or the supplementary cardholders never.
It gives up to 5 percent cashback on restaurants in the local and international markets as well as 2% for other international purchases and 1 cent on local expenditure and a lower 0.33 percent rate applicable to categories such as utility bills, government payments as well as education and fuel. There’s no minimum amount to spend and no maximum amount of earnings from cashback. This is a rarity in the market. Cardholders new to the card can also enjoy an initial welcome bonus after achieving the initial goal of spending.
- Cashback: Up to 5%
- Annual cost: AED 0
- Minimum wage: AED 5,000
- The best choice option for anyone who is looking for an absolutely free, uncapped cashback card

2. Emirates Islamic Cashback Plus Credit Card
This Shariah-compliant credit card has one of the top rate of interest in the market that can reach 10% back on your grocery eating, dining education, telecom charges.
The problem is that the highest rate only applies to AED 3000 of your monthly spending within these categories. total cashback is set at AED 200 per calendar month for all categories. The program is subject to an annual cost which is balanced by the perks of a lifestyle such as access to airport lounges as well as complimentary golf.
- Cashback: Up to 10% (capped at AED 200/month)
- Annual cost: AED 299
- Minimum wage: Not specified by the bank.
- is ideal option for households with a heavy food and dining expenses who want access to lounges

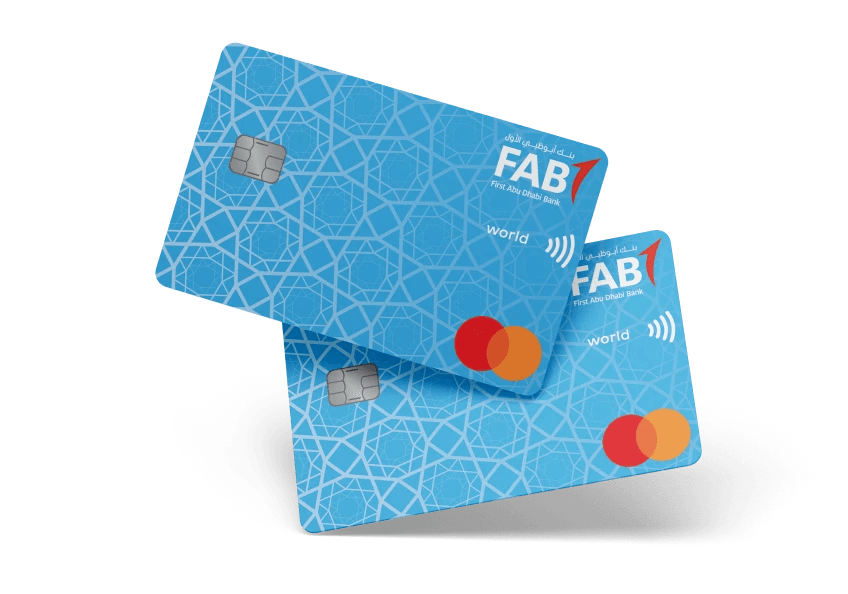
3. FAB Cashback Credit Card
FAB’s cashback credit card is focused on categories that are lifestyle-related, providing 5% cashback on clothing food, dining out, and groceries and 3% cashback on international travel and 1% cashback on all other purchases.
Cashback for the top categories is limited to AED 200 per category, with the overall limit of AED 1,000. This is which is a pretty generous amount when in comparison to other competitors. The redemption process is instant through the FAB mobile application, an advantage that other issuers can’t match.
- Cashback: Up to 5%
- Annual cost: AED 300
- Minimum wage: AED 5,000
- Ideal For: Frequent shoppers who need quick, mobile-based redemption
4. CBD Al Islami Super Saver Credit Card
Commercial Bank Dubai’s Islamic cashback card is designed around household expenses, providing up 10% cashback for grocery purchases as well as school fees, fuel and utility bills.
The total monthly limit is in the range of AED 600, which is among the highest among all cards listed, making it a great choice for families with larger families that have multiple recurring costs. Annual fees are waived completely for the initial year.
- Cashback: Up to 10% (capped at AED 600/month)
- Annual cost: Free first year Then AED 400
- Minimum wage: AED 5,000
- Ideal to: families with monthly charges and school fees

5. RAKBANK Titanium Credit Card
The RAKBANK Titanium card offers daily cashback with an unusually powerful entertainment benefit that offers 50 percent cashback on eligible entertainment expenditure, plus the 5% discount on dining and groceries.
It’s required to have an annual minimum of AED 2,00 in order to get cashback. the maximum amount is AED 1,500, which is a lot for a card that has no annual fees whatsoever.
- Cashback up to percent (plus 50 percent on entertainment)
- Annual cost: AED 0
- Minimum wage: AED 8,000
- Ideal to: Diners, cinema-goers or those who would like a card with no fees
6. HSBC Live+ Credit Card
The HSBC Live+ card is aimed at customers who dine often out, offering cashback at 6% for dining out fuel, 5% off dining and 2% for education, food and entertainment.
Cashback is restricted to AED 200 per transaction cycle A minimum monthly expenditure of AED 3,300 is required for access to the highest rates. It’s among the highest-interest cards on the list, and it also rewards customers who pay their balance in full every month.
- Cashback: Up to 6%
- Annual cost: AED 299
- Minimum wage: AED 5,000
- Ideal to: Frequent diners who have their balance cleared each month

7. Dubai Islamic Bank Consumer Cashback Platinum Credit Card
The Shariah-compliant card offered by DIB gives the possibility of cashback up to 4 percent for the categories of car maintenance, supermarkets telephone bills, utilities, fuel and school feesA wide range of daily categories.
Categories can be capped between AED 150 – AED 400, based on kind of spend, with the total billing cycle cap at AED 1,000. The plan also offers medical and travel insurance as an added perk.
- Cashback: Up to 4% (capped at AED 1,000/cycle)
- Annual cost: AED 199
- Minimum wage: AED 15,000
- is ideal to: High-earning individuals who require coverage across a broad spectrum, as well as travel insurance

8. Standard Chartered Simply Cash Credit Card
As per its name the card is easy Cashback of 1% on domestic expenditure and 2% cashback on international transactions, without complicated tracking of categories.
This annual cost is eliminated the first year. It could be waived again following years if you reach the minimum annual spending threshold. The maximum cashback amount per month can be reached at AED 1,000.
- Cashback: Up to 2%
- Annual cost: Free first year Then AED 525 (waivable)
- Minimum wage: AED 8,000
- Ideal to: People who want simple flat-rate functionality over category optimization
9. ADCB TouchPoints Platinum Credit Card
It is technically a card based on points rather than a pure cashback credit card, ADCB TouchPoints deserves a mention as points can be used directly at the point of sale and converted into airline miles or used to pay bills -which is similar to cashback in real life.
Earnings rates differ according to category for retail transactions, and they earn the highest amount of points per dirham. The card comes with one of the highest annual fees listed on this list, even though its first year of use is completely free.
- Cashback equivalent Points-based, cap at AED 2,000/month.
- Annual cost: AED 600 (free the first year)
- Minimum wage: AED 8,000
- Ideal for: Cardholders who are looking for the flexibility to choose between miles, cashback and bill payment
10. Commercial Bank International Rewards Platinum Mastercard
This card stands out due to an exclusive, but useful benefit that gives 100 percent cashback on up to four tickets to the cinema every month, as well as cashback on food and drink spent at the cinema. There is no annual cost whatsoever.
In addition to Cinema perks, it’s regular value is lower than the other cards that are on this list, which is why it is best used as a second card, instead of your primary spending card.
- Cashback Focused on cinema (100% on certain tickets)
- Annual cost: AED 0
- Minimum wage: AED 15,000
- is ideal for Regular moviegoers who need an additional card that is free
Cashback Credit Card Comparison Table
| Card | Cashback Rate | Annual Fee (AED) | Min. Salary (AED) | Monthly Cap | Shariah-Compliant |
|---|---|---|---|---|---|
| Mashreq Cashback | Up to 5% | 0 | 5,000 | None | Yes |
| Emirates Islamic Cashback Plus | Up to 10% | 299 | Not stated | 200 | Yes |
| FAB Cashback | Up to 5% | 300 | 5,000 | 1,000 | Yes |
| CBD Al Islami Super Saver | Up to 10% | 400 (free Yr 1) | 5,000 | 600 | Yes |
| RAKBANK Titanium | 5 percent or more (50 percent entertainment) | 0 | 8,000 | 1,500 | No |
| HSBC Live+ | Up to 6% | 299 | 5,000 | 200/cycle | No |
| DIB Consumer Cashback Platinum | Up to 4% | 199 | 15,000 | 1,000 | Yes |
| Standard Chartered Simply Cash | Up to 2% | 525 (free Yr 1) | 8,000 | 1,000 | No |
| ADCB TouchPoints Platinum | Points-based | 600 (free Yr 1) | 8,000 | ~2,000 (value) | No |
| CBI International Rewards Platinum | Cinema-focused | 0 | 15,000 | Not stated | No |
Rates fees, rates, and eligibility requirements can changes at the bank’s discretion. Always confirm the current terms with the bank prior to applying.
How to Choose the Right Cashback Card for Your Spending?
With ten choices to choose from with ten options, the “best” card really comes down to your personal spending needs:
- Bill or grocery consumers need to consider CBD Al Islami Super Saver or DIB Consumer Cashback Platinum, both of which offer rewards for everyday household items.
- Regular customers receive the best value by using HSBC Liveand FAB Cashback, both of which have some of the most competitive rates for dining.
- Anyone looking for zero charges and has no limit should go with Mashreq Cashback that is one of the few truly unlimited, free-for-life alternatives.
- Families that have school charges and multiple recurring bills can benefit from cards with larger monthly caps overall like CBD’s AED600 ceiling, or RAKBANK’s AED 1,500.
- Simple-minded customers who do not want to track categories, should look into Standard Chartered Simply Cash for its flat-rate structure.
It’s also important to weigh the annual cost against your actual monthly expenditure. A card with a 10% cashback and caps out at 200 AED a month could yield lower than an fee-free two percent flat rate card, in the event that your spending is extensive instead of focusing on a single area.
Common Mistakes to Avoid With Cashback Cards
- A balance to be paid: The cost of interest on UAE credit cards usually are between 3 percent to 3.8 percent per month. which can wipe out any cashback you earn if do not pay the balance in the full amount.
- Not paying attention to limits on monthly spending: Many cardholders assume that the advertised rate applies to all expenditures however, they find it ceases to accrue once they’ve reached the limit.
- Avoiding exclusions categories like the government cash withdrawals, payment to the government, and occasionally utilities are excluded or have a lesser rate.
- Insufficiently redeeming by the deadline: Some cards expire unredeemed cashback after a certain time period (often between two and three years) It’s therefore worth making a regular effort to redeem your card instead of sitting it out.
- Selecting solely on headline rates: A 10% card with a lower cap may yield less than a basic 2% uncapped cardalways compare it to the actual pattern of your spending.
Final Thoughts
The best cashback credit card to use in the UAE is less dependent on the most attractive headline rate and more on the extent to which the card’s categories as well as fees, caps, and categories correspond to your actual expenditure. For the majority of residents an uncapped, free alternative such as Mashreq Cashback provides dependable value without risk of loss for those who are primarily expenditure on dining out, groceries or even bills could be better off with an expensive, cap-based card such as Emirates Islamic Cashback Plus or CBD Al Islami Super Saver. If you’re deciding on one, check the fine print on the bank’s website prior to making a decision, as rates and conditions on these cards change frequently.
Frequently Asked Questions
1. What is a credit card with cashback?
A credit card that cashback gives a percentage of your expenditure back to you, typically in the form of a statement credit once you purchase eligible items.
2. Are cashbacks taxable in the UAE is it?
In the UAE does not have personal income tax, therefore cashback earned from credit card purchases isn’t considered income that is tax-deductible.
3. Can expats get money-back credit cards within the UAE
Yes, expats can apply to apply for UAE cashback credit card as long as they meet the issuing bank’s minimum wage and residency requirements.
4. Do I require a pay stub to be eligible for cashback cards not always?
Certain cards, such as Mashreq Cashback does not require a transfer of salary, however, you’ll need to provide proof of your the minimum amount of income by presenting bank statements.
5. What is the credit score I require to get an UAE cashback reward card?
Although the requirements differ for each bank but one thing to consider is an Al Etihad Credit Bureau (AECB) score of about 680 or greater is typically advised for cashback cards with premium features.
6. How do you redeem cashback?
UAE cashback cards are redeemable as statement credits once you have reached a minimum threshold, although certain banks also allow direct bank transfer.
7. What is different between cashback cards and Rewards points credit cards?
Cashback card provide the benefit of a cash-value refund and points-based cards require the conversion of points into miles, vouchers or bill payment which may add more the complexity.
8. Do cashback cards have foreign transaction fees?
The majority do, but some have a higher rate of cashback on international purchases to compensate for this rate, like Mashreq’s 2 percent rate for international transactions.
9. Can I carry multiple cashback cards simultaneously
Yes, a lot of UAE residents carry one card that is used for daily spending and a second card that is specifically designed for a benefit, like dining or cinema cashback.
10. What happens when I fail to pay the amount in full?
You’ll be charged interest per month typically between 3 to 3.8 percent typically surpasses any cashback that you’ve earned in that month.